Discover how IT services for small business, especially backup and disaster recovery plans, can influence your insurance and loan rates significantly.

October 23, 2026
A small business without a documented backup and disaster recovery plan can see higher borrowing and insurance costs, even if no data loss ever happens. The risk is priced in quietly, long before any crisis.
Most small business owners assume IT services exist to keep systems humming and data secure. What that assumption misses is a quieter effect: how you handle backup and disaster recovery can shape what you pay for loans or insurance.
A documented backup and disaster recovery plan isn't just a technical checklist tucked away in a server closet. It's evidence lenders and insurers may look for, whether or not they ever ask you directly, and its absence can make a business look riskier on paper. That perceived risk doesn't stay abstract. It shows up in the numbers on your next quote.
So IT services for small business turn out to be about more than uptime. They're about demonstrating readiness to anyone who has a stake in whether your business survives its next bad week.
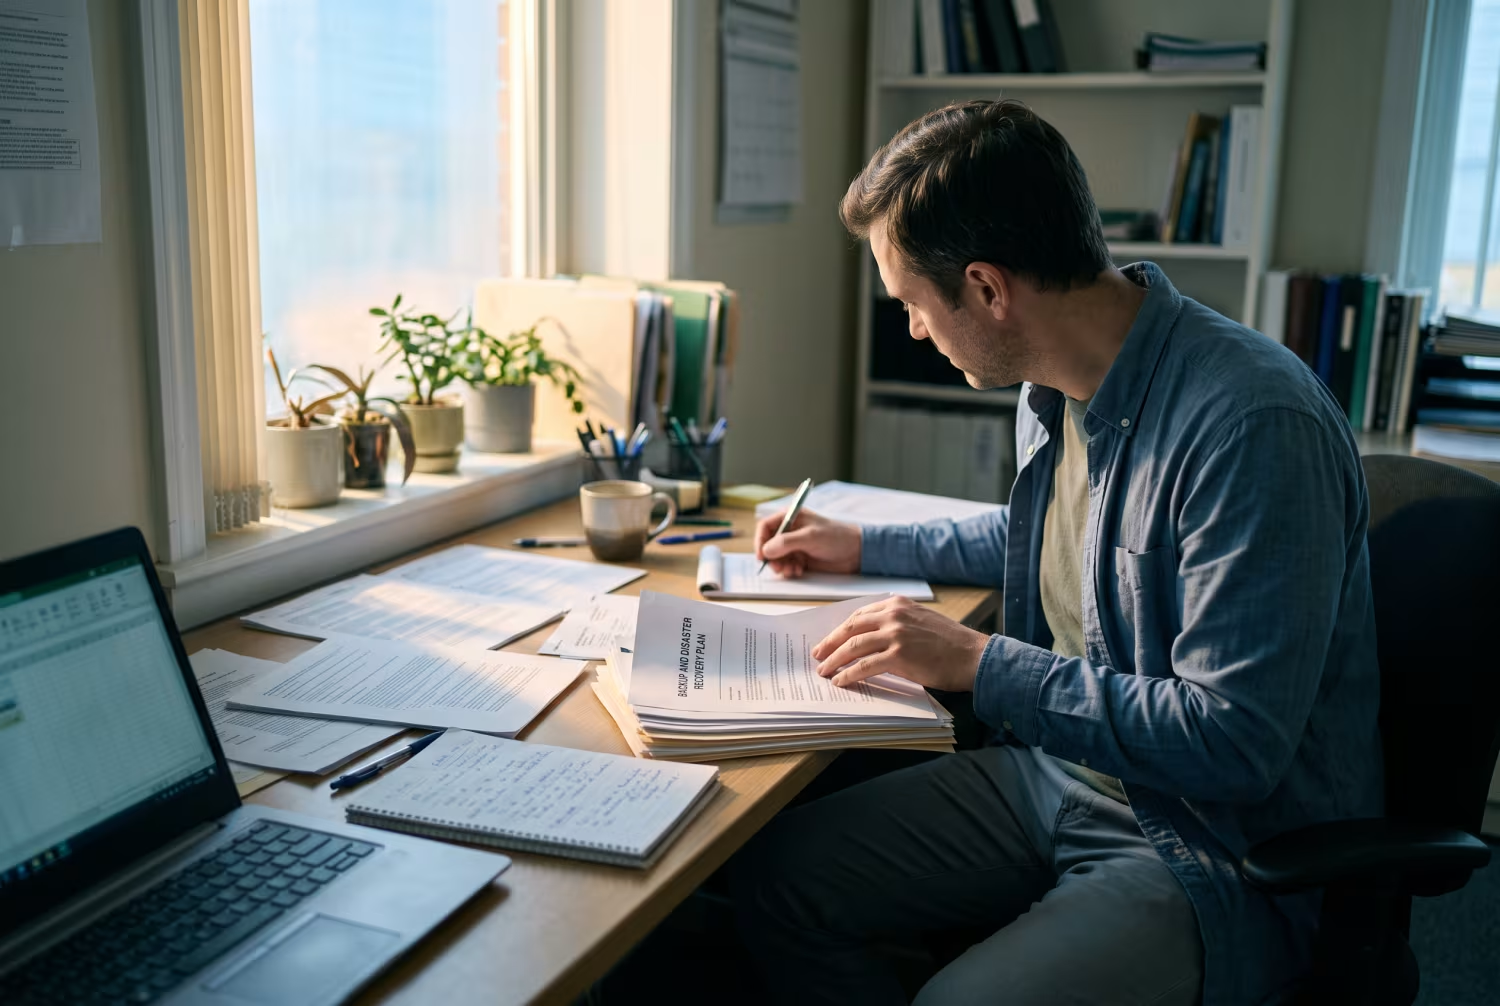
Plenty of business owners invest in reliable systems but never write down how backup and recovery actually work. That gap matters, because documentation isn't just an internal reference — it carries weight well beyond your own team.
When you apply for credit or insurance, providers want evidence of how you'd handle a crisis. Even without a direct request for your IT plan, its presence or absence can feed into the risk models and checklists lenders and insurers use behind the scenes.
Consequently, a business that can't produce a clear, current plan risks getting flagged as higher risk. That flag rarely stops at eligibility — it can nudge your rates upward quietly, long before any actual disaster tests the plan.
Skipping the documentation doesn't just leave you exposed to data loss. It can start costing you money well before anything breaks.
That's because lenders and insurers watch for signs of proactive risk management, and a missing or outdated plan reads as a lack of preparation. In practice, that reading translates into higher costs for borrowing or coverage.
The increases are rarely dramatic at first. Interest rates creep up a fraction of a point, or premiums drift higher renewal after renewal. Add those small shifts together over several years, though, and the expense becomes hard to ignore.
Revenue and assets only tell part of the story a lender or insurer reads. Risk management fills in the rest, and in Nashville, where regulations and expectations can shift quickly, visible preparation carries real weight.
A documented backup and disaster recovery plan signals that a business takes risk seriously, showing the provider that potential failure points have been mapped and a recovery path already exists. That signal can make a business more attractive to lenders and insurers even if the plan never gets used.
Without it, though, the questions start piling up. Is the business prepared for a cyberattack? Could it recover quickly from a hardware failure? Absent clear answers, that business starts looking like the bigger gamble.
The impact rarely announces itself right away, yet over time, missing documentation works its way into the bottom line through several channels:
Individually small, these effects compound quietly, adding real expense year after year.
A documented plan is more than a list of backup jobs. It's a set of steps and resources proving readiness, and a solid version usually covers the following ground.
List the hardware, software, and data essential to daily operations. Knowing what matters most tells you what to protect first.
Spell out how often backups run, where they're stored, and how their integrity gets verified. That detail shows preparation rather than optimism.
Lay out the exact steps a team takes when something goes wrong, from restoring files to contacting support services. That sequence turns a vague intention into an actual process.
Assign specific tasks to specific people so everyone knows their job in a crisis. Clarity here is what prevents confusion when time matters most.
Explain how staff, customers, and partners stay informed while an incident unfolds. Steady communication is often what keeps the business running through the disruption.
Show how the plan gets tested and kept current, since untested plans tend to fail exactly when they're needed. Regular review is what keeps the document trustworthy rather than decorative.
Documenting a backup and disaster recovery plan can feel like extra effort when nothing has gone wrong yet. Even so, that effort tends to pay off in ways that reach well past the IT department.
Because lenders and insurers are more inclined to treat a prepared business as a safe bet, proactive risk management can open doors elsewhere: better rates, more flexible terms, fewer surprises exactly when help is needed most.
If it's unclear where a business currently stands, one question cuts through the uncertainty: could a clear, up-to-date plan be handed over today if a lender or insurer asked for it?
Left unaddressed, the cost of missing documentation compounds. Higher credit and insurance costs can persist for years even without a single major data-loss event, and those extra dollars quietly erode margins that might otherwise fund growth.
Folding backup and disaster recovery planning into regular IT services addresses both sides of that equation at once — protecting the data itself while also protecting the business's financial standing and reputation.
If your business has 40 to 100 users, you may be wondering if your current IT documentation is enough to satisfy lenders or insurers. At Axios Technology Partners, we understand how small gaps in your backup and disaster recovery planning can quietly raise your costs.
We invite you to see how we approach this challenge, or to start a conversation about your own documentation and risk profile.
Get free ongoing security awareness training for your whole team when you work with us—helping you build a stronger defense against threats before they become costly.
Insurance providers weigh how well a business manages risk, and a documented plan demonstrates preparation for unexpected events, often qualifying a business for better rates. Without one, a business may be treated as higher risk and charged higher premiums.
Documentation should identify which systems and data are critical, detail how and when backups happen, assign responsibility for each step, and explain how communication will work during a crisis. Regular testing and updates keep the plan effective over time.
Managed IT service providers can build, document, and maintain a backup and disaster recovery plan, along with testing it regularly and aligning it with industry standards for audits or reviews.
Lenders want assurance that a business can survive disruptions without extended downtime. A clear plan for handling IT problems signals a lower chance of prolonged outages, making the business a safer investment.
The right choice depends on a business's specific needs and resources: outsourcing brings specialized expertise and current tools, while in-house support offers more direct control. Many small businesses blend both to balance cost and coverage.